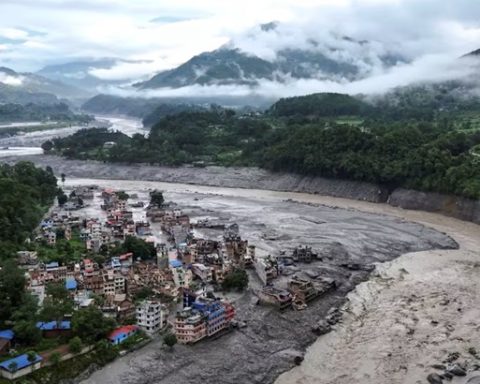
Apart from wars and conflicts between countries and regions, another matter of profound concern confronting the international community is global warming, with average global temperatures continuing to rise significantly over the years. Although the world has convened numerous United Nations climate conferences, with around 30 Conferences of the Parties held in different countries over the past few decades, the international community has yet to implement a sufficiently effective and universally accepted strategy capable of reversing the underlying trend. The gap between political commitments and measurable progress remains one of the central problems in global climate policy. Governments repeatedly announce ambitious targets for reducing greenhouse gas emissions, yet global energy consumption continues to rise, fossil fuels remain deeply embedded in national economies, and emissions continue to increase.
The United Nations Environment Programme has warned that a breach of the 1.5°C global warming threshold could result in irreversible ecological losses that no adaptation measures would be capable of fully reversing. The significance of this warning is particularly serious because climate change is not simply a matter of gradual temperature increases. Rising temperatures can alter rainfall patterns, intensify extreme weather events, accelerate the loss of biodiversity, increase pressure on agricultural systems and water resources, and contribute to sea-level rise. The World Meteorological Organization has also forecast a possible positive Indian Ocean Dipole, a climate phenomenon capable of altering rainfall and temperature patterns across large areas of the Indian Ocean region and neighbouring countries. Such developments illustrate the complexity of climate change, where atmospheric, oceanic and human-induced factors interact in ways that can produce consequences extending far beyond national borders.
At COP30, the 30th United Nations Climate Change Conference held in Belém, Brazil, in 2025, the consensus Global Mutirão decision became the first COP text to acknowledge that a temporary overshoot of the 1.5°C limit was likely. This acknowledgement is significant because the 1.5°C objective has become one of the central reference points in international climate policy. The possibility of temporarily exceeding that threshold demonstrates the widening gap between the ambition of climate agreements and the realities of global energy consumption and economic development. The fundamental difficulty is that the modern global economy remains heavily dependent on fossil fuels. Coal, crude oil and natural gas continue to provide the overwhelming majority of the world’s energy, while hydrogen produced from fossil fuel feedstocks, particularly brown, grey and blue hydrogen, also remains part of the industrial energy system. The continued use of these energy sources generates substantial greenhouse gas emissions and remains a principal driver of global warming.
Methane presents an additional and particularly serious climate challenge. It is a highly potent greenhouse gas, and methane emissions originate from both natural and human sources. Among the largest human-caused sources are agriculture, particularly livestock production and rice cultivation. This means that the climate problem cannot be addressed exclusively by replacing petrol and diesel vehicles or reducing coal-fired electricity generation. It also requires changes across agriculture, industry, transport, energy production, land use and other sectors of the global economy. Nevertheless, the complete elimination of crude oil, natural gas and coal from the global energy system would represent one of the most significant steps towards achieving the frequently discussed objective of net zero emissions. The central question, however, is whether such a transformation is technologically, economically and politically possible.
Several major economies have already announced target years for reaching net zero emissions. The United States and the European Union have set 2050 as their respective target years, while China has established 2060 and India has established 2070. Japan has also adopted 2050 as its target year. These commitments demonstrate that the concept of net zero has become firmly embedded in international climate policy. However, the pace of progress remains a matter of concern. Announcing a target several decades into the future is considerably easier than restructuring an energy system that has been built around fossil fuels for more than a century. The disparity between long-term political commitments and current patterns of energy production and consumption raises a fundamental question about whether existing policies are sufficient to deliver the promised transformation.
The available emissions data illustrate the scale of the challenge. Global greenhouse gas emissions, including carbon dioxide, methane, nitrous oxide and fluorinated gases, increased from 48,962.10 million tonnes of CO2 equivalent in 2020 to 52,540.80 million tonnes in 2023 and then to 53,206.40 million tonnes in 2024. According to the supplied EDGAR data, global fossil CO2 emissions have increased by 74.9 per cent since 1990. These figures demonstrate that the world has not yet entered a sustained period of global emissions reduction. Instead, despite decades of international negotiations and increasingly ambitious climate commitments, total emissions continue to move in the opposite direction from what would be required to achieve rapid decarbonisation.
The underlying energy consumption figures are equally revealing. Global energy consumption stood at 563.9 exajoules in 2014 and increased to 569.1 exajoules in 2015. It declined slightly to 563.2 exajoules in 2016 before rising again to 576.8 exajoules in 2017 and 599.1 exajoules in 2018. Consumption reached 610.9 exajoules in 2019, fell temporarily to 585.7 exajoules in 2020 during the disruption caused by the COVID-19 pandemic, and then recovered to 603.8 exajoules in 2021. It increased further to 619.3 exajoules in 2022, 629.3 exajoules in 2023 and 639.3 exajoules in 2024. The figures therefore indicate a broad upward trend in global energy demand, notwithstanding temporary disruptions. Global energy demand has generally been increasing at an average rate of around 1 to 2 per cent annually, with overall global demand reported to have risen by 1.3 per cent in 2025.
The composition of global energy production explains why reducing emissions has proved so difficult. In 2020, coal accounted for 174.9 exajoules of energy production, natural gas for 154.7 exajoules and crude oil for 189.6 exajoules. Nuclear power contributed 28.41 exajoules, while renewables and other sources accounted for 38.12 exajoules, producing a total energy supply of 585.73 exajoules. By 2021, coal production had increased to 181.1 exajoules, natural gas to 161.1 exajoules and crude oil to 192 exajoules, while nuclear power accounted for 29.54 exajoules and renewables and other sources for 40.19 exajoules, bringing total energy production to 603.93 exajoules. In 2022, coal reached 184.8 exajoules, natural gas 161.9 exajoules and crude oil 201.3 exajoules. Nuclear power accounted for 28.37 exajoules and renewables and other sources for 42.98 exajoules, with total production reaching 619.35 exajoules.
The upward trend continued in 2023, when coal production reached 189.1 exajoules, natural gas 162.1 exajoules and crude oil 204.4 exajoules. Nuclear power contributed 29.03 exajoules and renewables and other sources 44.71 exajoules, resulting in total energy production of 629.34 exajoules. In 2024, coal increased further to 191.6 exajoules, natural gas to 164.7 exajoules and crude oil to 205.1 exajoules. Nuclear power reached 29.95 exajoules, while renewables and other sources rose to 47.93 exajoules, bringing total global energy production to 639.28 exajoules. The figures show that although renewable energy is expanding, fossil fuel production has not declined in absolute terms.
The 2024 energy mix makes the problem particularly clear. Coal accounted for approximately 30 per cent of global energy production, natural gas for 26 per cent and crude oil for 32 per cent. Nuclear power accounted for about 5 per cent, while renewable energy and other sources accounted for approximately 7 per cent. On the basis of these figures, coal, crude oil and natural gas together represented approximately 88 per cent of the feedstock used for global energy generation. This dependence explains why the transition to net zero is so difficult. It is not merely a matter of replacing one technology with another. It requires the transformation of an enormous global economic system involving electricity generation, transport, manufacturing, agriculture, construction, shipping, aviation and industrial production.
Crude oil consumption provides another illustration of this contradiction. Global consumption stood at 93.99 million barrels per day in 2020, representing a year-on-year decline of 6.4 per cent. As economies recovered, consumption increased to 95.69 million barrels per day in 2021, representing growth of 1.8 per cent. It rose again to 100.42 million barrels per day in 2022, an increase of 4.9 per cent, followed by 102.45 million barrels per day in 2023, an increase of approximately 2 per cent. Consumption reached 103.08 million barrels per day in 2024, representing growth of 0.61 per cent, before rising to 106.12 million barrels per day in 2025, an increase of approximately 3 per cent. These figures indicate that global crude oil consumption has been steadily increasing after the pandemic-related decline, with the broad trend amounting to approximately 2 per cent annual growth over the period considered.
The contradiction is particularly striking because many of the world’s largest oil-producing countries have simultaneously committed themselves to long-term net zero objectives while continuing to produce and export substantial quantities of crude oil. For economies heavily dependent on oil revenues, rapidly reducing production would have profound implications for government revenue, employment, foreign exchange earnings, industrial investment and national economic stability. The political difficulty of achieving an energy transition therefore cannot be separated from the economic structure of major fossil fuel-producing countries.
Natural gas consumption shows a broadly similar pattern. Global consumption increased from 3,943.58 billion cubic metres in 2020 to 4,133.26 billion cubic metres in 2021. It declined slightly to 4,090.16 billion cubic metres in 2022 before rising to 4,141.22 billion cubic metres in 2023 and 4,232.50 billion cubic metres in 2024. The supplied data do not provide a 2025 consumption figure. Global natural gas production reportedly increased by approximately 1.3 per cent in 2025, following an increase of 1.8 per cent in 2024, with much of the additional production coming from North America, the Middle East and China. Once again, the evidence points towards continued expansion rather than a decisive reduction in fossil fuel dependence.
Coal presents an even more striking example. Global coal consumption stood at approximately 7,557.85 million tonnes in 2020, a year-on-year decline of 3.7 per cent. It increased to 7,906.43 million tonnes in 2021, representing growth of 4.6 per cent, and rose again to 8,207.59 million tonnes in 2022, an increase of 3.8 per cent. Consumption reached 8,608.37 million tonnes in 2023, representing growth of 4.9 per cent, and increased further to 8,815.95 million tonnes in 2024, an additional 2.4 per cent increase. Global coal production therefore reached record levels during the past decade, peaking at approximately 9.2 billion tonnes in 2024 to 2025 according to the figures cited. The continued importance of coal is especially significant because it is among the most carbon-intensive major energy sources, yet countries with large coal industries continue to depend on it for electricity generation and industrial development.
There are several technological alternatives that could reduce dependence on fossil fuels, including green hydrogen, renewable energy from wind and solar power, bioenergy, nuclear power, electric vehicles and ethanol. Each of these technologies offers genuine opportunities for reducing greenhouse gas emissions, but none is without limitations. The central question is therefore not whether alternatives exist, because they clearly do, but whether they can be deployed on a sufficient scale, at an acceptable cost and with adequate reliability to replace fossil fuels across the global economy.
Green hydrogen is frequently presented as one of the most promising alternatives. Hydrogen can be classified according to the feedstock and production method used. Brown, grey and blue hydrogen are generally associated with fossil fuel feedstocks, while green hydrogen is produced using water and renewable electricity, with biomass also potentially forming part of some low-carbon hydrogen pathways. Brown hydrogen produced from coal has a particularly high carbon footprint because of the emissions associated with its production. Green hydrogen, by contrast, offers the possibility of producing hydrogen without relying directly on fossil fuel feedstocks when renewable electricity is used in the production process.
The share of green hydrogen in global hydrogen production has reportedly increased significantly. According to the figures supplied from S&P Global Energy and the Statistical Review of World Energy 2026, green hydrogen accounted for approximately 9.14 per cent of total hydrogen production in 2023, increasing to 13.14 per cent in 2024 and reaching approximately 29.3 per cent in 2025. Green hydrogen production in 2025 was reported at approximately 317,000 tonnes worldwide. Asia Pacific accounted for about 200,700 tonnes, Europe for 73,500 tonnes and North America for 28,900 tonnes, while other regions, including Central and South America, the Commonwealth of Independent States, the Middle East and Africa, accounted for approximately 13,900 tonnes. The figures indicate that production is expanding and that a significant number of new green hydrogen projects are under planning or implementation in several countries.
Despite this growth, the economics of green hydrogen remain a major obstacle. In 2026, the supplied price estimates indicate that green hydrogen cost approximately US$4 to US$6 per kilogram in the United States, US$6 to US$6.90 per kilogram in the European Union and approximately US$4 per kilogram in China. By comparison, brown hydrogen was estimated at approximately US$1.25 to US$2 per kilogram in the United States, US$1.50 to US$3.50 per kilogram in the European Union and US$1.80 to US$2.10 per kilogram in China. Grey hydrogen was estimated at around US$2 per kilogram in the United States, US$3.68 per kilogram in the European Union and approximately US$1.70 to US$2.10 per kilogram in China. These figures demonstrate the fundamental economic disadvantage facing green hydrogen, whose production cost remains substantially higher than that of conventional hydrogen produced from fossil fuel feedstocks.
Another major issue is the availability of renewable electricity. Green hydrogen projects require a consistent and sufficiently large supply of renewable power. Solar, wind and hydropower generation, however, are affected by weather conditions, seasonal variations and fluctuations in resource availability. A green hydrogen plant therefore requires either a sufficiently large and reliable renewable electricity supply or additional storage and balancing infrastructure. These requirements can significantly increase the overall cost of production.
Government policy is another important factor. Many green hydrogen projects depend heavily on government support through favourable policy measures, capital subsidies, tax incentives and operational support designed to reduce the cost gap between green hydrogen and hydrogen produced from fossil fuels. Europe, for example, has provided substantial financial support for green hydrogen projects through European Union funding programmes and national government schemes. The long-term sustainability of such support is nevertheless uncertain. Governments face competing demands on public finances, and fiscal pressures can change significantly over time. If subsidies are reduced or withdrawn, projects that depend heavily on government assistance may struggle to remain commercially competitive.
There is also the question of whether existing consumers of conventional hydrogen will be willing or able to switch to green hydrogen. Grey, brown and blue hydrogen are used extensively in industries such as ammonia and methanol production and in steel manufacturing and other industrial processes. If green hydrogen remains considerably more expensive, industrial consumers may have limited economic incentives to make the transition unless governments introduce strong regulatory or financial measures. Consequently, the future of green hydrogen depends not only on technological development but also on the cost of renewable electricity, improvements in electrolysis technology, economies of scale, infrastructure development and the willingness of governments and industries to absorb the transition costs.
Green hydrogen is therefore environmentally attractive, and the large-scale replacement of grey, brown and blue hydrogen with green hydrogen could significantly reduce fossil fuel consumption and associated emissions. Nevertheless, complete substitution cannot be assumed. The current price differential remains substantial, and replacing conventional hydrogen throughout existing industrial systems could alter the economics of numerous downstream industries. The technology for green hydrogen production is continuing to develop, and process optimisation could reduce production costs considerably. If the cost of green hydrogen can eventually approach that of conventional hydrogen, its prospects would become far stronger. At present, however, it is difficult to say with confidence that green hydrogen alone can eliminate the world’s dependence on fossil fuels.
Renewable electricity provides another potentially transformative pathway. Global renewable power capacity increased from approximately 2,810.899 GW in 2020 to 3,077.120 GW in 2021, 3,379.389 GW in 2022, 3,872.829 GW in 2023 and 4,457.340 GW in 2024. It increased further to approximately 5,149.280 GW in 2025. These figures from the International Renewable Energy Agency’s Renewable Capacity Statistics 2026 demonstrate the extraordinary pace at which renewable power capacity has expanded. Yet the increase in installed capacity should not be confused with an equivalent increase in actual energy production, because renewable technologies do not operate continuously at their maximum rated capacity.
The share of renewable energy in total global energy production has also increased, although from a relatively low base. Renewables and other sources accounted for 38.12 exajoules out of a total 585.73 exajoules in 2020, representing approximately 6.50 per cent of total energy production. In 2021, renewables and other sources reached 40.19 exajoules out of 603.93 exajoules, increasing their share to 6.65 per cent. In 2022, the corresponding figures were 42.98 exajoules out of 619.35 exajoules, representing 6.93 per cent. In 2023, renewable and other energy sources accounted for 44.71 exajoules out of 629.34 exajoules, giving them a 7.10 per cent share. By 2024, the figure had increased to 47.93 exajoules out of 639.28 exajoules, representing approximately 7.49 per cent of total energy production.
Solar power has expanded particularly rapidly. In 2024, solar power reportedly achieved approximately 30 per cent growth, surpassing the growth or contribution associated with wind power at 8.4 per cent and approaching nuclear power at 8.8 per cent in the comparative figures cited. Nevertheless, renewable energy continues to face fundamental limitations. Wind and solar generation depend on weather and seasonal conditions, while hydropower depends on water availability. The effective capacity utilisation of some renewable technologies can also be considerably lower than that of conventional thermal or nuclear power plants. The supplied assessment places renewable capacity utilisation in the region of 22 to 25 per cent. Consequently, replacing fossil fuel generation entirely would require not only enormous increases in installed renewable capacity but also energy storage, grid reinforcement, transmission infrastructure and other technologies capable of balancing intermittent generation.
Nuclear power provides another low-carbon alternative, but its global contribution remains comparatively limited. Nuclear power production stood at 28.41 exajoules out of total global energy production of 585.73 exajoules in 2020, representing approximately 4.8 per cent. In 2021, nuclear production increased to 29.54 exajoules out of 603.93 exajoules, maintaining a share of approximately 4.8 per cent. In 2022, nuclear power contributed 28.37 exajoules out of 619.35 exajoules, reducing its share to approximately 4.5 per cent. In 2023, nuclear production reached 29.03 exajoules out of 629.34 exajoules, representing approximately 4.6 per cent, while in 2024 it reached 29.95 exajoules out of 639.28 exajoules, again representing approximately 4.6 per cent. Nuclear generation reportedly increased by 1.3 per cent in 2025 compared with growth of 2.6 per cent in 2024.
Nuclear power has the advantage of producing electricity with very low direct greenhouse gas emissions during operation and can provide large quantities of reliable electricity. However, nuclear projects are generally expensive, technologically demanding and subject to stringent safety requirements. The nuclear accidents at Fukushima in Japan and Chernobyl in the former Soviet Union significantly affected public confidence and slowed the expansion of nuclear power in many countries for years. New nuclear projects are nevertheless being proposed or implemented in several countries. Even so, given that nuclear power currently represents only around 4 to 5 per cent of total global energy production in the figures cited, it is difficult to argue that nuclear energy alone could eliminate fossil fuel dependence on a global scale.
Electric vehicles provide another example of a technology that can reduce emissions while simultaneously creating a new demand for electricity. Global electric vehicle production increased from approximately 6.75 million units in 2021 to 10 million in 2022, 14 million in 2023, 17 million in 2024 and 20 million in 2025. Production is projected in the supplied figures to reach approximately 23 million units in 2026. The rapid increase demonstrates the accelerating global transition towards electric mobility. Electric vehicles can reduce local air pollution and, over their lifetimes, can produce lower carbon emissions than conventional fossil fuel vehicles, particularly when the electricity used to charge them comes from low-carbon sources. Unlike internal combustion engines, electric vehicles do not directly emit carbon dioxide, nitrogen oxides or soot particles from the vehicle while operating on the road.
The climate benefits of electric vehicles, however, depend partly on how the electricity used to charge their batteries is generated. If electric vehicles are charged predominantly using electricity generated from coal, natural gas or other fossil fuels, a significant portion of the emissions associated with transport is effectively transferred from the vehicle to the power-generation system. This does not necessarily eliminate emissions, but changes where they occur. The rapid expansion of electric vehicle ownership therefore increases electricity demand, and where renewable electricity capacity is insufficient to meet that additional demand, thermal power generation may continue to play a substantial role. A comprehensive assessment of electric vehicles must consequently consider the entire energy system rather than treating the vehicle itself as an isolated source of emissions.
Ethanol provides another partial alternative to fossil fuel. Approximately 85 per cent of global ethanol production is used for fuel blending and transportation. The United States and Brazil are major drivers of this demand, primarily through the use of corn and sugarcane. Ethanol blending levels vary considerably between countries, with many countries using blends ranging from approximately 10 to 27 per cent. Brazil has adopted blends in the E27 to E30 range for regular petrol and also provides E100 for flex-fuel vehicles, while India has introduced E20 petrol containing 20 per cent ethanol. Ethanol can therefore reduce the amount of conventional petrol required for transportation, but its potential for substantially displacing fossil fuels is constrained by agricultural production. Ethanol production depends heavily on the availability of crops such as sugarcane and corn, and agricultural land is itself subject to competing demands for food, animal feed and other uses. If global crop acreage remains broadly stable, ethanol production may also remain relatively constrained, limiting its ability to transform the global energy system.
The central question is therefore whether the global net zero objective is genuinely feasible and attainable. There is no doubt that the objective is environmentally necessary if the world is to prevent further dangerous climate change. There is also no doubt that countries have made significant technological progress in renewable energy, electric mobility, energy storage, nuclear power and green hydrogen. The difficulty lies in the enormous scale of the transformation required. Global energy consumption continues to rise, while fossil fuels still account for approximately 88 per cent of the global energy mix in the figures presented. At the same time, many of the alternatives intended to replace fossil fuels remain constrained by cost, intermittency, infrastructure requirements, resource availability, technological limitations or dependence on government policy.
The economic interests of major fossil fuel-producing countries represent another formidable obstacle. Large coal-producing economies such as China and India and major crude oil and natural gas producers such as Saudi Arabia, Russia and Qatar cannot easily reduce fossil fuel production without potentially imposing substantial costs on their national economies. Fossil fuel revenues support government budgets, employment, foreign exchange earnings, infrastructure investment and industrial activity in many producer states. A rapid reduction in production could therefore have consequences extending well beyond the energy sector. This economic reality helps explain why the political commitments made at international climate conferences frequently appear more ambitious than the actual reductions in fossil fuel production.
The United States also represents an important complication in the global climate equation. The country has historically been one of the world’s largest cumulative greenhouse gas emitters, and changes in its climate policy have significant international consequences. Its withdrawal from the Paris Agreement and subsequent moves to distance itself from several international climate mechanisms demonstrate how vulnerable global climate commitments remain to changes in domestic political leadership. When one of the world’s largest economies and historical emitters changes its climate policy, the consequences extend beyond its own borders and can influence the willingness of other countries to maintain ambitious commitments.
The fundamental contradiction is therefore increasingly difficult to ignore. The world has established increasingly ambitious climate targets while simultaneously consuming more energy and continuing to expand the production and consumption of fossil fuels. Renewable energy capacity is growing rapidly, green hydrogen is developing, nuclear power remains an important low-carbon source, electric vehicle production is expanding and ethanol is reducing a portion of petroleum demand. Yet none of these alternatives has so far demonstrated the capacity to displace fossil fuels on the scale required to reverse the global trend in energy consumption and greenhouse gas emissions.
The essential takeaway is that the global net zero objective should not be dismissed simply because achieving it is difficult. The environmental consequences of continued warming make emissions reduction unavoidable. However, there is a substantial difference between establishing an aspirational target and demonstrating a credible pathway towards achieving it. The statistics on global energy consumption, fossil fuel production, greenhouse gas emissions and the current contribution of alternative energy sources suggest that the world remains a considerable distance from complete decarbonisation. The critical issue is therefore not whether net zero is desirable, but whether the technological, economic and political conditions required to achieve it can be created quickly enough.
The world may eventually reach a stage at which technological innovation, falling renewable energy costs, improved energy storage, advanced nuclear technology, commercially competitive green hydrogen, electrification and more efficient energy systems fundamentally alter the global energy balance. Such a transformation, however, cannot be taken for granted. It will require sustained investment, technological breakthroughs, political consistency and a willingness to confront the economic interests that remain deeply connected to fossil fuel production. Until those conditions are established, the proposition of achieving global zero emissions remains less a demonstrated outcome than an exceptionally ambitious aspiration. The uncomfortable question, therefore, is whether global net zero is presently a realistic and attainable objective or whether it remains, at least under current conditions, a utopian ambition that the international community repeatedly promises but has yet to demonstrate that it can deliver.