India’s exports surged 26% in August, helped by a sharp increase in shipments to the United States, a weaker rupee and lower gold imports, according to data released Tuesday by the Ministry of Commerce. Goods exports rose to $43.81 billion from $34.74 billion in August 2025, marking a significant acceleration as Indian exporters faced substantially lower US tariffs than a year earlier.
Exports to the US rose by more than 21% to $8.3 billion in August, compared with $6.8 billion a year earlier. It was the sharpest monthly export increase to Washington recorded by India so far this calendar year. The rise came as Indian goods faced tariffs of 10%, compared with the much higher rates imposed during August 2025 amid heightened tensions between India and the United States.
The first set of 25% reciprocal tariffs came into effect on August 7, 2025. By August 27, an additional 25% tariff related to Russian oil imports had taken effect, bringing the overall tariffs to 50%. The sharp rise in exports this August therefore comes against a lower base, with last year’s higher tariffs already weighing on Indian shipments.
The depreciation of the Indian currency also supported export growth. The rupee had fallen by more than 10%, although economists said the benefits of a weaker currency are likely to be more pronounced for higher-margin products. An HSBC report said high-tech exports, which account for around half of core exports, have shown a relatively stronger uplift following rupee depreciation, particularly in machinery, electronics and transport over a two- to three-quarter period.
The export recovery, however, remains uneven across sectors. During the April to June quarter, engineering goods, electronics and pharmaceuticals grew 18.1%, 22.6% and 6.8%, respectively, while several labour-intensive industries contracted. Textile exports fell 12.4% and leather products declined 4.7%. Exports of fruits and vegetables, ceramics and glassware, and jute products dropped 10.3%, 25% and 13.4%, respectively, while tea exports fell 17.5%. Overall, 11 of 31 export sectors recorded year-on-year declines during the quarter.
Imports also increased, but at a slower pace than exports. Goods imports rose 14.05% to $70.67 billion in August from $61.96 billion a year earlier. Gold imports fell sharply to $2.30 billion from $5.44 billion, marking the first significant decline in gold imports during the ongoing financial year.
“Goods import growth is lower than export growth. This has helped the goods trade deficit decline from $26.86 billion in August this year compared to $27.20 billion in August 2025,” Commerce Secretary Rajesh Agarwal told the press.
The Federation of Indian Export Organisations said the 26.12 per cent growth in merchandise exports demonstrated the resilience, competitiveness and adaptability of Indian exporters. Its president, S C Ralhan, also pointed to stronger export growth across China, Singapore, Germany, South Africa, Malaysia, Tanzania, Hong Kong, Australia, Spain and Sri Lanka as evidence of greater diversification.
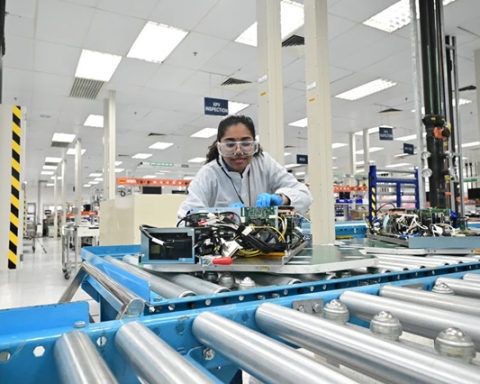
Automobile exports rose 22.2% year on year, led by two- and three-wheelers, while gems and jewellery exports increased 3.14% to $2.30 billion. Electronics and engineering exports continued to expand, alongside chemicals, pharmaceuticals and other manufacturing-intensive sectors. Meanwhile, petroleum and energy products, electronic goods and industrial inputs continued to drive significant import demand, reflecting domestic production and consumption requirements.