A central bank is not merely an institution that adjusts interest rates, issues currency and lectures the public about financial discipline. It is a guardian of public confidence. When ordinary people lose their savings through questionable financial schemes, the question is not simply why they invested. It is why the system meant to protect them failed to intervene in time, and why justice can become another financial burden for those already robbed.
Sri Lanka today faces serious questions about conflicts of interest at the highest levels of its Central Bank. Allegations made by representatives of agricultural investment companies whose accounts have reportedly been frozen raise concerns about the relationships between regulators, corporate directors and powerful commercial interests. These allegations do not establish corruption or prove that any board member has improperly influenced a decision. But they demand answers. When people entrusted with protecting the public also hold positions in major private enterprises, transparency cannot be optional. The public must be able to establish whether decisions are impartial, whether interests are properly declared and whether the rules apply equally to everyone.
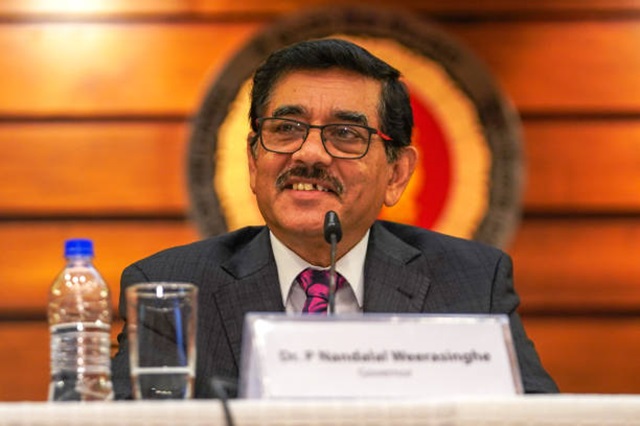
The Central Bank of Sri Lanka Act No. 16 of 2023 established two principal decision-making bodies, the Governing Board and the Monetary Policy Board. The former oversees the administration and general policies of the Central Bank, while the latter formulates monetary policy, including decisions affecting the supply and cost of money. According to the Central Bank’s institutional structure, Governor Dr P. Nandalal Weerasinghe chairs both boards, and the six appointed members of the Governing Board also sit on the Monetary Policy Board.
The corporate connections identified in the allegations deserve particular scrutiny. Nihal Fonseka is reported to hold directorships at Brandix Lanka Ltd, Phoenix Industries Ltd, Phoenix Ventures Ltd, Mobitel (Pvt) Ltd and Sri Lanka Telecom PLC. Dr Ravi Rathnayake is identified as a former chairman of the board of Kanrich Finance Ltd, which reportedly became insolvent following restructuring, and as an adviser to the World Bank, the Asian Development Bank and USAID. Anushka Wijesinha is reported to serve as a director of Hayleys Fibre PLC and Fairfirst Insurance Ltd, companies associated in the supplied material with businessman Dhammika Perera.
Vish Govindasamy is reported to hold directorships at Sunshine Holdings PLC, Colombo Dockyard PLC, Mazagon Dock Shipbuilders Ltd in India, Dialog Axiata PLC, Softlogic Life Insurance PLC, United Motors Lanka PLC and TAL Lanka Hotels PLC, associated with the Taj hotel brand. He is also identified as a director of the Board of Investment of Sri Lanka. Manil Jayesinghe is reported to serve on the boards of John Keells Holdings PLC, DIMO PLC, C.W. Mackie PLC, Lanka IOC PLC, Vallibel One PLC, Ceylon Hospitals PLC, associated with Durdans, Royal Ceramics Lanka PLC, Lanka Milk Foods (CWE) PLC and Lanka Dairies (Pvt) Ltd. Maithri Evan Wickremesinghe is identified as a director of Convenience Foods Lanka PLC. These affiliations are presented as reported in the material supplied and should be checked against current corporate disclosures and official records before being treated as a complete, verified register of interests.
Why does this matter? Because conflicts of interest do not require a secret meeting, a criminal conspiracy or an explicit exchange of favours to become a legitimate public concern. They arise when a person’s private responsibilities, commercial relationships or financial interests could influence, or reasonably appear to influence, the exercise of public duties. A director of a major commercial enterprise may possess valuable expertise. That expertise can benefit public institutions. But it can also create competing obligations when regulatory policy, credit conditions, financial stability or decisions affecting a connected business are under discussion.
Consider the possible implications. Monetary policy influences borrowing costs, investment conditions, exchange-rate expectations and the financial environment in which businesses operate. General Central Bank policies can affect confidence, financial regulation and the broader economic conditions faced by corporate groups. These effects do not mean that a particular director has manipulated a decision or that every company represented by a board member receives preferential treatment. They do mean that clear disclosure, independent scrutiny and enforceable recusal procedures are indispensable. The public should not have to rely on personal assurances that conflicts will never arise.
Adam Smith warned in The Wealth of Nations in 1776 about the danger of business interests organising themselves against the public. His argument remains relevant because commercial influence can be concentrated, while the interests of depositors are fragmented. John Maynard Keynes challenged the assumption that financial markets invariably produce rational outcomes. Hyman Minsky later explained how periods of apparent stability can encourage risk-taking that ultimately threatens the wider system. Together, these thinkers remind us that financial crises are not simply the product of individual mistakes. They can emerge from institutional weaknesses, distorted incentives and the failure to confront risks early.
There is, however, an important legal distinction. The Central Bank Act contains disqualifications intended to prevent appointed members from holding positions in entities regulated by the Bank or in financial institutions operating in Sri Lanka. The Central Bank also describes a framework under which Governing Board members participate in the Monetary Policy Board, while technical analysis and recommendations are prepared through the Bank’s internal monetary policy process. The law provides for institutional autonomy and accountability. These safeguards matter, but their existence does not eliminate the need to examine how they operate in practice.
The question is whether the public can independently verify that relevant interests are declared, conflicts are properly managed and members withdraw from decisions when required. Does the Central Bank maintain sufficiently detailed records of declarations and recusals? Are those records subject to independent audit? Are the public explanations of its governance arrangements adequate to establish confidence? Where a board member’s business interests overlap with a matter under consideration, what independent mechanism determines whether participation is appropriate? These are reasonable questions, not allegations of guilt.
The issue becomes even more serious when placed alongside the experience of depositors caught in suspected unlawful financial operations. A company collects money from the public. Regulatory restrictions arrive only after deposits have been accepted and losses may already have occurred. Depositors turn to law enforcement agencies and courts, where proceedings can consume years and impose further financial burdens. Meanwhile, those associated with the company may claim that they cannot act because the Central Bank has prohibited the operation.
That sequence leaves the public with a devastating question. Why does the system appear capable of restricting an operation after damage has occurred but struggle to deliver timely recovery and accountability? The sequence alone does not prove collusion between regulators and financial operators. But every delay, missed warning and unexplained enforcement failure should be investigated. Authorities must establish when complaints first emerged, whether additional deposits were accepted after credible warnings, whether assets were preserved, whether connected companies were examined and whether suspected transfers of money were traced.
Every director, promoter and beneficial owner of a failed or unlawful financial operation must face a fair and evidence-based examination of their role. Their direct and indirect assets should be investigated where the law permits, and their documented sources of wealth should be compared with legitimate earnings and business transactions. Assets acquired through genuine commercial achievement must be distinguished from assets allegedly obtained through fraud, misappropriation or concealment. Wealth is not proof of wrongdoing. Nor should wealth, reputation or corporate influence shield anyone from a lawful investigation.
The Central Bank must publish meaningful information about enforcement timelines, complaints, regulatory interventions and referrals to law enforcement, subject to legitimate confidentiality requirements. An independent review should examine whether its safeguards against conflicts of interest work effectively and whether enforcement action against unlawful financial operations is sufficiently prompt. Proven misconduct must have consequences, regardless of a person’s position.
The essential takeaway is simple. Central Bank independence must never become independence from public accountability. Its board members deserve fair treatment, and allegations against them must be assessed through evidence rather than insinuation. But the institution must also demonstrate that private interests cannot override public responsibilities. Depositors should not be abandoned to years of litigation while those responsible retain the benefits of delay. A central bank that protects confidence must first prove that it protects the public.